

Estimating custom kitchens and furniture is more than calculating the cost of boards, hardware, and labor. A good estimating process must help a furniture maker prepare quotations efficiently, set a competitive selling price, understand the financial consequences of each project, and protect the long-term profitability of the business.
There is also an important distinction between an estimate and a quotation. An estimate is the internal calculation of the expected costs, selling price, and financial outcome of a job. A quotation is the client-facing offer derived from that estimate.
A well-designed estimating system should therefore do two things: calculate the project costs as accurately as practical and allow the selling price to be adjusted according to market conditions, workload, project characteristics, and business priorities.
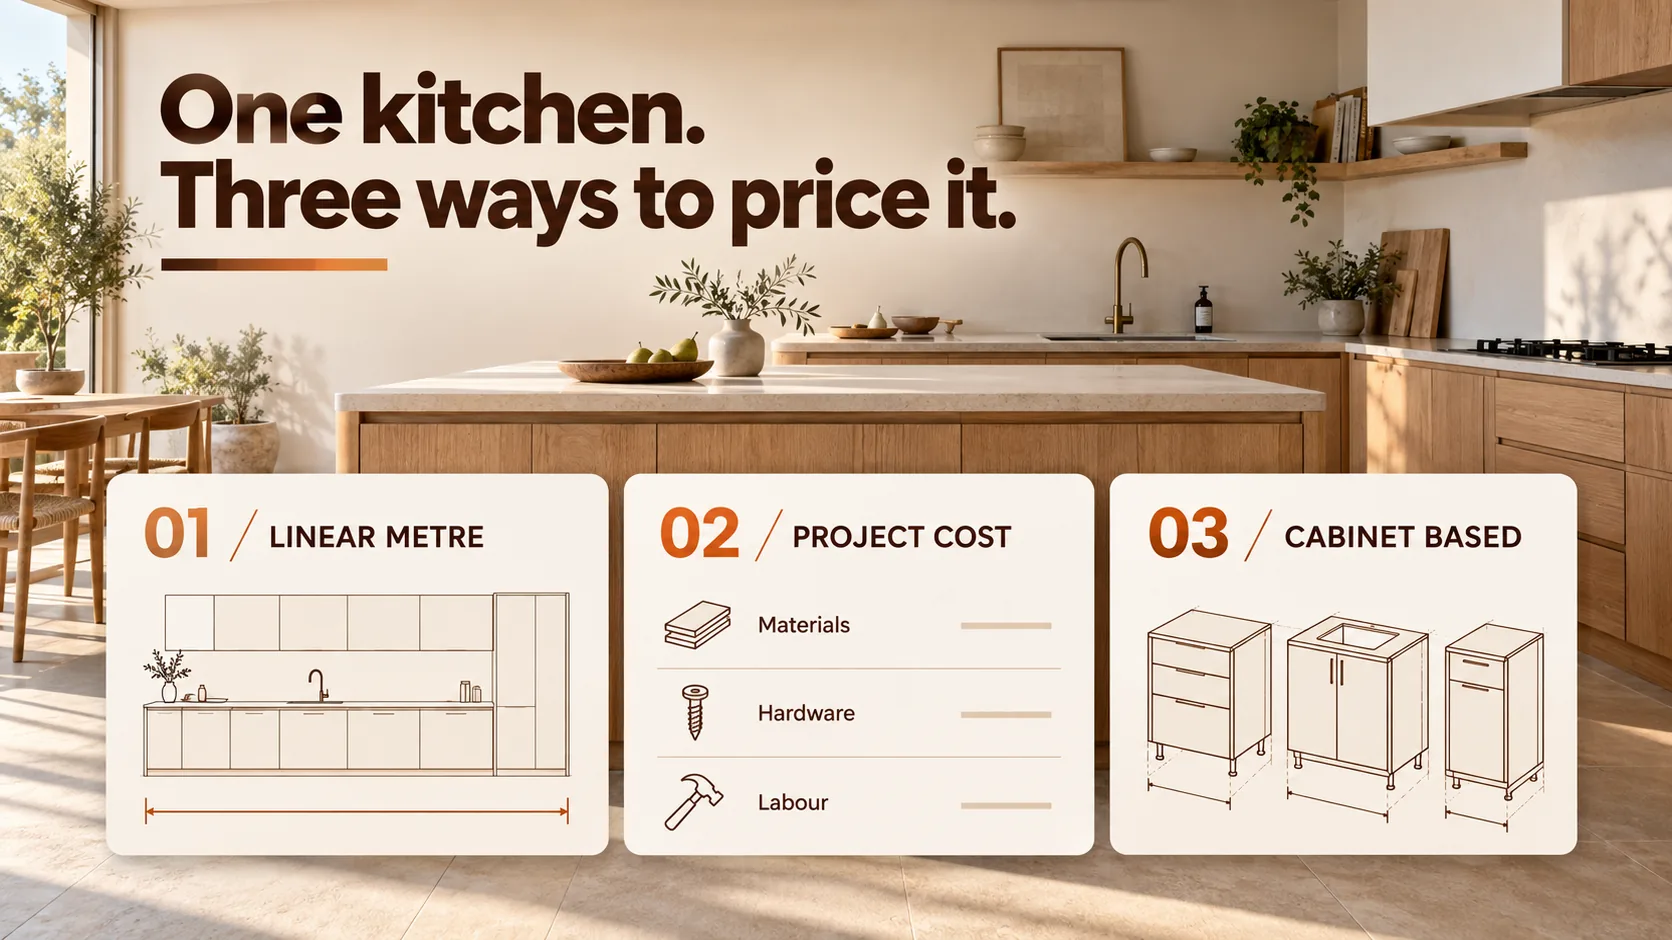
Three useful methods form the foundation of such a system.
1. Price per Linear Meter
Pricing per linear meter is one of the simplest ways to estimate a kitchen. The furniture maker establishes a benchmark price per meter and multiplies it by the length of the kitchen.
However, a useful benchmark must be based on a sound calculation of costs. It should not simply be an arbitrary price chosen by looking at competitors.
Different construction materials and specifications require different rates. For example, a kitchen made from melamine-faced particleboard may have a different benchmark from one made using MDF, especially if the latter requires additional finishing. The benchmark must also clearly define what is included: carcasses, doors, standard hardware, finishing, installation, transport, or other services.
Additional charges can then be applied for items outside the standard specification, such as special hardware, unusual finishes, non-standard dimensions, or complex construction details.
We cover this method in depth, including how to build the benchmark and handle surcharges, in Price per Linear Meter: A Simple Way to Estimate Custom Kitchens.
Advantages
- Fast estimating: A preliminary price can be prepared with relatively little information.
- Simple communication: Customers can understand the basic pricing logic.
- Consistent starting point: Similar projects can be estimated using the same benchmark.
- Useful for early enquiries: It helps determine whether a potential project is broadly within the customer’s budget before investing heavily in detailed planning.
Disadvantages
The main weakness is that a linear meter does not represent the same amount of work in every kitchen. Two kitchens of equal length can differ significantly in the number of cabinets, drawers, corners, special fittings, finishing requirements, and installation challenges.
A simple straight kitchen may require less work than a kitchen of the same length with irregular walls, multiple corners, integrated appliances, and complicated access.
If the benchmark is too broad, the business may underprice complex projects or overprice simple ones. Adjustments can reduce this problem, but as the number of exceptions grows, the method becomes less simple.
Best use: Price per linear meter works well for preliminary estimates and relatively standardized projects, provided the benchmark is derived from realistic costs and the limits of the standard specification are clear.
2. Detailed Project Costing with a Pricing Multiplier
Detailed project costing starts with the specific project rather than a general benchmark. The furniture maker calculates the expected cost of the work and then applies a pricing strategy to determine the selling price.
The cost base may include:
- Raw materials and sheet goods
- Material processing, cutting, edging, drilling, and other preparation
- Hardware, fittings, drawer systems, hinges, and accessories
- Direct labor and subcontracted work
- Finishing and other production services
- Transport, installation, and other project-specific costs
- An appropriate allocation of overheads, depending on the purpose of the calculation
The precise cost base must be defined consistently. If some expenses are excluded from the calculation, the furniture maker must understand how they will be covered elsewhere.
Once the cost has been estimated, a multiplier can be applied. For example:
Selling price = defined cost base × pricing multiplier
A multiplier of 2, 3, or 4 produces very different selling prices. The appropriate multiplier depends on what the cost base contains, the business’s cost structure, market conditions, available capacity, project risk, and the required financial return.
It is important not to confuse a multiplier with profit. If the defined cost base is €1,000 and the selling price is €3,000, the multiplier is 3. The difference is €2,000, representing a 200% markup on that cost base and a 66.7% gross margin relative to the selling price. It does not mean the business will make €2,000 in net profit. Expenses not included in the cost base, such as overheads, administration, and other operating costs, still have to be covered.
Advantages
- Project-specific costing: Materials, hardware, processing, and labor can be calculated for the actual design.
- Greater transparency: The furniture maker can see which parts of the project contribute most to its cost.
- Flexible pricing: The selling price can be adjusted without changing the underlying cost calculation.
- Better financial analysis: The business can compare expected and actual costs to improve future estimates.
Disadvantages
Detailed costing can require substantial work before the customer commits to the project. It may involve a site visit, precise measurements, design development, detailed drawings, material selection, and discussions about specifications.
This creates a commercial problem: the business may spend many hours preparing an estimate for a customer who eventually chooses another provider or abandons the project.
The method can also create a false sense of precision. A detailed calculation is only as reliable as its assumptions. Uncertain installation conditions, incomplete customer decisions, supplier price changes, and unforeseen work can still cause actual costs to differ from the estimate.
For a step-by-step walkthrough with a worked example, see Detailed Project Costing: From Actual Costs to the Selling Price.
Best use: Detailed project costing is especially useful for complex, unusual, or high-value projects where understanding the individual cost structure justifies the time spent estimating.
3. Cabinet-Based Estimating
Cabinet-based estimating offers a practical middle ground between a simple price-per-meter method and detailed costing from scratch. It is also a strong foundation for an estimating application designed specifically for custom furniture and kitchens.
The central idea is to build a reusable library of cabinet types and furniture elements. Instead of estimating every project as a completely new collection of parts, the furniture maker selects and configures known elements.
A library might contain base cabinets, wall cabinets, tall units, drawer cabinets, corner cabinets, appliance housings, open shelves, end panels, fillers, and other frequently used elements. Each element has parameters such as width, height, depth, material, construction type, hardware, and finishing requirements.
Behind each cabinet template, the system can store the information needed to calculate its cost and selling price, including:
- Material quantities and expected waste
- Cutting, edging, drilling, and other processing requirements
- Hardware and fittings
- Labor assumptions
- Finishing and subcontracting costs
- Standard construction rules
- Pricing rules and any applicable adjustments
The furniture maker then assembles a kitchen from these elements. The application combines their specifications to produce a project-level estimate, a material and hardware purchasing list, and, where the data supports it, information for production preparation.
Why this method is powerful
The main advantage is reuse. The business calculates and organizes much of its product knowledge in advance, then applies it repeatedly.
A cabinet library also improves consistency. If the same cabinet type is used in several projects, its underlying construction and costing logic can be maintained centrally. When the business learns from production experience, the library can be updated with better material quantities, more realistic labor assumptions, and improved construction rules.
Over time, the library can grow to include increasingly specialized elements. It may be developed manually, imported from furniture-specific CAD software, or connected to other design and production tools.
Limitations and initial investment
The main disadvantage is the initial effort required to build a useful library. Cabinet templates need to be defined, their construction logic documented, and their costs tested against actual production.
This investment is not unique to cabinet-based estimating. Every serious estimating method requires some combination of reliable cost data, clear assumptions, and experience. The difference is that a cabinet library turns much of this knowledge into reusable digital assets.
Even a comprehensive library will not cover every situation. Custom furniture inevitably includes unusual dimensions, special details, unexpected site conditions, and one-off design decisions. The system must therefore allow the user to add manual items, exceptional costs, and project-specific adjustments without forcing every situation into a standard template.
We explain how to build and test a cabinet library in Cabinet-Based Estimating: Build a Reusable System for Custom Furniture.
Best use: Cabinet-based estimating is particularly suitable for businesses that repeatedly build kitchens or similar furniture and want to reduce administrative work while improving consistency and financial visibility.
Its long-term potential goes beyond estimating. When cabinet specifications are structured properly, the same information can support purchasing, production planning, and workshop preparation. The ultimate goal is to automate as much repetitive work as possible while leaving the furniture maker in control of design decisions, exceptional cases, and final approval.
Other Estimating and Pricing Methods Worth Understanding
The three methods above are not the only ways to approach estimating. Several other concepts can complement them.
Time-and-materials pricing
The customer is charged for materials and the time spent on the project, often with agreed rates or markups. This can be appropriate when the scope is uncertain, although customers may prefer a defined price in advance.
Labor-hour-based estimating
The business estimates the hours required for design, preparation, production, finishing, installation, and other activities, then applies an appropriate labor rate. This can improve the accuracy of other methods, particularly when labor is a major part of the total cost.
Component-based estimating
The project is priced through individual components such as carcasses, doors, drawer boxes, panels, hardware, and finishing. This approach can form part of a cabinet-based system, especially when components have their own cost and production rules.
Target-margin pricing
Instead of applying a simple multiplier, the business calculates the selling price required to achieve a target gross margin.
Selling price = cost base ÷ (1 − target margin)
For example, if the defined cost base is €1,000 and the target margin is 40%, the required price is approximately €1,667. This only achieves the intended margin relative to the specified cost base; excluded expenses must still be accounted for.
Value-based pricing
The price may also reflect the value the customer places on design, craftsmanship, customization, service, and the finished result. Two projects with similar costs may justify different prices if their perceived value or market position differs.
Value-based pricing should not replace cost awareness. A business still needs to understand its costs and assess whether the price is commercially worthwhile.
Fixed-price quotations
A fixed price is a commercial arrangement rather than a separate costing method. The business can calculate the price using linear meters, detailed costing, cabinet templates, or a combination of methods, then offer the customer a fixed amount for an agreed scope of work.
Because the provider accepts some uncertainty about the final cost, assumptions, exclusions, and change-order rules become particularly important.
Profitability Is More Than the Difference Between Price and Cost
A project may appear profitable because its selling price is substantially higher than its estimated cost. However, profitability, risk, and overall effort must be considered together.
Not all projects that show the same expected profit represent the same opportunity for the provider. One job may be straightforward, predictable, and close to the workshop, while another may involve uncertain site conditions, difficult installation, extensive customer coordination, or a long journey. Even if the two projects show the same expected financial result, the second may require more time, create more uncertainty, and expose the business to greater potential losses.
It is therefore useful to assess a project from several perspectives:
- Expected profitability: What financial return is expected after the relevant costs are accounted for?
- Risk: How likely is it that costs, timing, scope, or payment will differ from expectations, and how significant could the consequences be?
- Overall effort: How much time, coordination, travel, planning, and management attention will the project require?
- Capacity and opportunity cost: What other work could the business complete during the same period, and would accepting this project displace a better opportunity?
- Cash flow and payment exposure: How much money must be committed before the business receives payment, and how long might that money remain tied up?
Some of these factors can be estimated or recorded. For example, travel distance, expected installation hours, number of site visits, or a contingency allowance can be included in the cost calculation. Others are harder to express accurately as fixed parameters. A long-distance project might appear attractive on paper, but the travel, disruption to the work schedule, accommodation, or difficulty returning to resolve a problem may make it less attractive in practice.
Risk and effort are closely related, but they are not identical. A predictable project can require a great deal of work without being particularly risky. Conversely, a seemingly simple project can carry significant risk if the customer has unclear expectations, access is uncertain, or installation conditions have not been verified.
A good estimating system should capture the factors that can be quantified, make important assumptions visible, and allow the provider to apply informed judgment to the rest. Where uncertainty is significant, the response might be a higher price, a contingency allowance, clearer contractual conditions, a narrower scope, or a decision not to accept the job.
Profitability Must Also Be Evaluated Over Time
A single project’s profitability does not tell the whole story of a business. The provider should evaluate performance both per job and across a defined period, such as a month, quarter, or year.
A project can be profitable in isolation but still be a poor use of limited capacity if it consumes too much time, creates disruption, or delays more attractive work. Conversely, a project with a lower margin may be commercially useful if it fills otherwise idle production capacity, creates a valuable customer relationship, or leads to repeat business—provided that its price still supports the business’s financial needs.
The relevant question is not simply, “How much profit will this job make?” It is also, “How does accepting this job contribute to the overall performance of the business during the period being considered?”
Period-based analysis should look at actual revenue, direct costs, gross profit, operating expenses, net profit, available capacity, and cash flow. It should also compare estimates with actual results. This helps the provider identify whether the business is consistently pricing work correctly, whether certain types of projects consume disproportionate effort, and whether the total workload is generating the expected return.
Pricing can then respond to current conditions. During a quiet period, a lower price may be commercially reasonable if the work still covers the relevant costs and contributes positively to the business. During a busy period, the provider may charge more because capacity is scarce and accepting one job means turning down another. Neither decision should be based on a universal multiplier alone; the choice depends on the cost structure, workload, risk, and business objectives.
Other Factors That Are Difficult to Quantify
Even a sophisticated estimating application cannot turn every consideration into a reliable numerical parameter. Some aspects of a project depend on experience, incomplete information, human behavior, or circumstances that become clear only after work begins. These factors should not be ignored simply because they are difficult to measure.
Examples include:
- Customer communication and decision-making: Some customers make decisions promptly and provide clear instructions; others require repeated meetings, frequent changes, or extensive explanation.
- Uncertainty in site conditions: Walls, floors, services, access routes, and existing structures may differ from the information available during estimating.
- Design and installation complexity: A technically unusual detail may require more thought, troubleshooting, or coordination than its material cost suggests.
- Travel and disruption: A distant project can fragment the work schedule, increase fatigue, and make follow-up visits disproportionately expensive.
- Scope changes and expectations: A customer may expect small adjustments that collectively create substantial extra work, even if those changes are not obvious at the outset.
- Coordination with other trades: Delays or mistakes by other contractors can affect installation, require repeat visits, and leave the provider waiting or rearranging work.
- Reputation and relationship value: Some projects may create useful referrals, showcase the business’s capabilities, or strengthen a long-term customer relationship. The future value is real but uncertain.
- Schedule pressure and operational disruption: A project with a tight deadline may interfere with workshop planning or delay other jobs.
- Uncertainty in rework and after-sales service: The probability and consequences of adjustments, warranty work, or customer complaints are not always easy to predict.
These factors mean that an estimate cannot be fully parametric. A parametric system calculates outcomes from defined inputs and rules, but not every important input can be measured consistently or known in advance.
The practical goal should not be to eliminate human judgment. It should be to automate what can be calculated reliably, record what can be observed, and leave room for informed decisions where uncertainty remains.
An application can help by providing notes, risk flags, manual adjustments, contingency fields, and a record of why a price was changed. Over time, actual project results may reveal patterns that make some previously subjective factors easier to estimate. For example, the business may discover that certain installation conditions usually require additional hours or that projects beyond a particular travel distance tend to incur repeat-visit costs.
The system should improve as experience accumulates without pretending that every project can be reduced to a perfect formula.
How Should a Furniture Maker Choose a Method?
The methods are best understood as complementary approaches rather than mutually exclusive choices.
| Situation | Useful approach |
|---|---|
| Early enquiry with limited information | Price per linear meter |
| Complex or unusual one-off project | Detailed project costing |
| Repeated kitchen and cabinet types | Cabinet-based estimating |
| Labor-intensive work | Labor-hour-based calculations |
| Uncertain scope | Time-and-materials or carefully qualified pricing |
| Need to protect a defined margin | Target-margin calculation |
| Strong design or craftsmanship differentiation | Value-based pricing alongside cost analysis |
A practical application can combine these approaches. For example, it can use a linear-meter rate for an initial estimate, replace it with a cabinet-based calculation as the design becomes clearer, and add manual adjustments for exceptional complexity or risk. Detailed costing and target-margin calculations can then help the provider check whether the proposed selling price is financially appropriate.
The important architectural principle is to keep the cost calculation separate from the selling-price decision. Costs describe the expected resources required to deliver the project. Pricing rules determine how those costs are translated into a commercial offer. Risk, effort, capacity, market conditions, and the required return can influence that decision without corrupting the underlying cost data.
The Long-Term Goal: Less Administration, Better Decisions
For a custom furniture business, an estimating application should do more than calculate a number. It should reduce repetitive administrative work, preserve the business’s accumulated knowledge, prepare consistent quotations, and help the owner understand the financial implications of accepting each project.
A structured cabinet library is a particularly useful foundation because the same information can support estimating, purchasing, and production preparation. As the system matures, much of the routine work could be automated, leaving the furniture maker to verify measurements, discuss choices with the customer, review exceptional circumstances, and approve the final quotation.
The goal is not to remove professional judgment. It is to reserve that judgment for the decisions where it matters most.
A strong estimating system combines reliable cost data, flexible pricing, awareness of risk and effort, and an understanding of profitability over time. It helps the furniture maker price each project intelligently, protect the business, and spend less time managing information that the business already knows.